Blog

  • New Construction Homes in Panama City FL (2026)

    What Should You Know About New Construction Homes in Panama City, FL?

    Quick Answer: New construction homes in Panama City, FL are actively being built across Bay County in 2026, with communities sprouting in areas like Lynn Haven, Southport, and near Tyndall AFB. These homes offer modern floor plans, updated building codes, and energy-efficient features, but buyers should understand the full process — from lot selection to final walkthrough — before signing a contract with a builder.

    Why Are Buyers Choosing New Construction in Panama City Right Now?

    Panama City and the surrounding Bay County area have seen steady demand for new construction over the past several years. Hurricane Michael (2018) accelerated rebuilding across the region, and that momentum has continued into 2026 with builders responding to both local demand and an influx of relocating families, retirees, and military personnel stationed at Tyndall AFB.

    Key reasons buyers are gravitating toward new builds include:

    • Modern open-concept floor plans designed for Florida living
    • Construction to current Florida Building Code standards, including stronger wind resistance requirements
    • Builder warranties that cover structural components, systems, and workmanship
    • Energy-efficient construction with better insulation, windows, and appliances
    • Less immediate maintenance compared to older resale homes

    Where Are New Construction Homes Being Built in Bay County?

    Lynn Haven

    Lynn Haven remains one of the most popular destinations for new construction in the Panama City metro area. The city has a well-established infrastructure, good schools, and a family-friendly atmosphere. New subdivisions continue to expand along the northern corridors, offering a mix of single-family homes at various price points.

    Southport

    Southport is attracting buyers who want more land and a quieter rural feel without being too far from Panama City amenities. New construction here often includes larger lots, and some communities offer custom or semi-custom home options. It’s a growing area worth watching in 2026.

    Callaway and Springfield

    Both Callaway and Springfield offer more affordable new construction options compared to Lynn Haven. These cities sit close to US-98 and provide easy access to both Downtown Panama City and Tyndall AFB. Buyers on tighter budgets or military families using VA loans often find these communities attractive.

    Near Tyndall AFB

    With Tyndall’s ongoing reconstruction and mission expansion, there is consistent demand for housing close to the base. Builders have responded with communities that cater specifically to military families, sometimes with features like flexible floor plans for larger households and proximity to base gates. Military buyers using VA loans should confirm that new construction communities are VA-eligible before proceeding.

    Downtown Panama City and St. Andrews

    Infill new construction — meaning new homes built on individual lots within established neighborhoods — is occurring in areas like St. Andrews and parts of Downtown Panama City. These projects tend to be smaller-scale but can offer a unique opportunity to get a brand-new home in a walkable, character-rich neighborhood setting.

    What Are the Tradeoffs of Buying New Construction in Panama City?

    New construction comes with real advantages, but it also has tradeoffs that every buyer should weigh honestly:

    • Price premium: New construction often costs more per square foot than comparable resale homes in the same area.
    • Build timelines: Depending on the builder and supply chain conditions, your home could take several months to over a year to complete.
    • Limited negotiation on price: Builders often hold firm on base pricing but may offer incentives on upgrades, lot premiums, or closing cost contributions — especially when using their preferred lender.
    • Landscaping and neighborhood maturity: New communities can feel sparse for several years while trees and landscaping grow in.
    • HOA fees and CDD fees: Some new communities include Community Development Districts (CDDs) that add to your annual costs. Always review the full cost picture before committing.

    How Do Flood Zones and Insurance Affect New Construction in Bay County?

    This is one of the most important considerations for any homebuyer in Panama City — new construction or not. Bay County has significant flood zone exposure, particularly in lower-lying areas and those near coastal water bodies, North Bay, and Deer Point Lake.

    When evaluating a new construction home, buyers should:

    • Review the FEMA Flood Insurance Rate Map (FIRM) for the specific parcel
    • Ask the builder what flood zone the lot is located in and whether the home is elevated above Base Flood Elevation (BFE)
    • Understand that new construction in higher flood zones will likely require flood insurance in addition to homeowners insurance
    • Request elevation certificates from the builder, which can affect your flood insurance premiums
    • Consult with a licensed Florida insurance agent early in the process — insurance costs in Bay County can be significant and should be factored into your overall housing budget

    Building to current Florida Building Code does provide some advantages for wind coverage, and some insurers may offer better rates for newer construction. Always get insurance quotes before finalizing your purchase.

    What Should New Construction Buyers in Panama City Do Before Signing?

    Get Pre-Approved First

    Even though you may be buying from a builder, mortgage pre-approval is essential. It clarifies your budget, helps you evaluate builder incentive offers tied to their preferred lender, and puts you in a stronger negotiating position. Compare rates independently — you are not required to use a builder’s lender.

    Hire Your Own Real Estate Agent

    The builder’s sales representative works for the builder. Having your own buyer’s agent — ideally one with local Bay County experience and familiarity with new construction contracts — costs you nothing as a buyer in most cases, and provides meaningful representation throughout the process.

    Get an Independent Home Inspection

    New construction homes are not exempt from defects. Hiring an independent licensed home inspector — ideally at the pre-drywall stage and again at completion — can identify issues before they become expensive problems. Do not skip this step simply because the home is brand new.

    Review the Builder’s Contract Carefully

    Builder contracts are written to protect the builder. Have a real estate attorney review the contract before signing, particularly around timeline guarantees, price lock provisions, and what happens if construction is delayed.

    Frequently Asked Questions About New Construction Homes in Panama City, FL

    Are new construction homes in Panama City built to withstand hurricanes?

    Homes built after Hurricane Michael must comply with the updated Florida Building Code, which includes stronger requirements for wind resistance. That said, no home is hurricane-proof, and buyers should understand their specific risk based on location, flood zone, and proximity to the coast. Consulting with a licensed insurance agent about wind mitigation features is a smart step.

    Can military buyers use VA loans for new construction in Panama City?

    Yes, VA loans can be used for new construction, but the process has additional steps compared to purchasing a resale home. Not all builders are set up to work with VA construction loans. Military buyers near Tyndall AFB should work with a VA-experienced lender and confirm builder eligibility early in the process.

    How long does it take to build a new home in Bay County?

    Build timelines vary by builder, community, and customization level. Production builders offering inventory homes or spec homes may close in a few months, while semi-custom or custom builds can take 9 to 18 months or longer. Always get timeline expectations in writing and ask about what triggers extensions.

    What is a spec home versus a custom home in new construction?

    A spec home (speculative home) is one a builder constructs without a specific buyer in place, making design decisions themselves. Buyers purchase these move-in-ready or near-completion. A custom home is designed and built to your specific selections from the ground up. Semi-custom falls in between, where you choose from the builder’s predetermined options.

    Should I get a home inspection on a new construction home?

    Absolutely. Building inspections performed by the county ensure code compliance, but they are not the same as a thorough buyer’s inspection. A licensed home inspector can catch issues that code inspections miss. Many buyers in Bay County opt for both a pre-drywall inspection and a final walk-through inspection before closing.

    Do new construction communities in Panama City have HOAs?

    Many do, though not all. HOAs can provide neighborhood maintenance and amenity standards but also add monthly or annual costs. Some communities also have CDDs (Community Development Districts), which are assessed separately and can add hundreds of dollars per year to your tax bill. Always ask the builder for a full disclosure of all ongoing fees before signing.

    Is now a good time to buy new construction in Panama City in 2026?

    Market conditions change, and what makes sense depends on your personal situation, timeline, and financial readiness. The Panama City area continues to attract new residents, and builder activity reflects that demand. Speaking with a local real estate professional and a licensed lender will give you the most accurate, current picture of what you can afford and what’s available.

    PanamaCityFLHomes.com is built to help you research the local market and make a more confident real estate decision.
    Related Reading

  • Cost of Living in Panama City Florida 2026

    What Is the Cost of Living in Panama City, Florida?

    Quick Answer: Panama City, Florida offers a cost of living that is generally below the national average in several key categories, including housing, making it an attractive option for retirees, military families near Tyndall AFB, and relocating households. While groceries and utilities are close to national norms, property insurance costs in Bay County have risen significantly due to coastal flood risk and hurricane exposure. Overall, most residents find Panama City more affordable than larger Florida metros like Tampa, Orlando, or Miami.

    How Does Panama City’s Cost of Living Compare to the Rest of Florida?

    Florida has a wide range of living costs depending on the city. Panama City sits in the Florida Panhandle, and its smaller-city character means residents typically pay less for housing and daily expenses than those living in South Florida or the I-4 corridor. That said, Bay County has its own financial considerations that newcomers should understand before making a move.

    How Does Panama City Stack Up Against Major Florida Cities?

    • Housing: Median home prices in Panama City are generally lower than in Tampa, Jacksonville, or Miami, giving buyers more square footage for their budget.
    • Groceries: Grocery costs are close to the Florida and national average, with major chains like Walmart, Publix, and Winn-Dixie all serving the area.
    • Transportation: Gas prices and car insurance in Bay County track near state averages. Panama City is a car-dependent area, so owning a vehicle is essentially a necessity.
    • Healthcare: Access to healthcare has improved since the expansion of facilities post-Hurricane Michael, though some residents still travel to Tallahassee or Pensacola for specialized care.
    • Utilities: Electric bills can be higher in summer due to humidity and heat. Most homes use central air conditioning, which is a significant monthly expense from May through September.

    What Does Housing Cost in Panama City and Bay County?

    Housing is one of the biggest draws for people considering a move to Panama City. Compared to coastal Florida markets in South Florida or even the Space Coast, Bay County home prices remain more accessible for median-income households.

    What Are Home Prices Like Across Bay County Neighborhoods?

    Prices vary meaningfully depending on which neighborhood or community you target. Here is a general overview of how different areas compare:

    Area General Price Range Character
    Lynn Haven Mid to upper range Suburban, family-friendly, strong post-Michael rebuilding
    Callaway Affordable to mid range Working-class roots, improving infrastructure
    Springfield More affordable entry points Smaller lots, older homes, close to Tyndall AFB
    Parker Affordable Waterfront access on North Bay, smaller community
    Downtown Panama City Mixed, revitalization ongoing Historic, walkable pockets, condo and older home inventory
    St. Andrews Mid range with premium waterfront Historic neighborhood, marina access, eclectic character
    Southport Mid to upper range Newer construction, rural feel, no city taxes in some areas

    Buyers should note that post-Hurricane Michael rebuilding has brought a mix of newly constructed homes and older properties to the market simultaneously, which creates real pricing variation even within the same zip code.

    What Should Buyers Know About Insurance Costs in Bay County?

    This is one of the most important cost-of-living factors that surprises newcomers to Panama City. Florida homeowners insurance has increased dramatically statewide, and Bay County is no exception. Because the area is subject to hurricane risk and portions of the county lie within FEMA-designated flood zones, buyers can face insurance premiums that add meaningfully to their monthly housing costs.

    How Do Flood Zones Affect the Cost of Living?

    • Homes in FEMA Special Flood Hazard Areas (Zone A or AE) are typically required to carry separate flood insurance if financed with a federally backed mortgage.
    • Flood insurance can range from a few hundred to several thousand dollars per year depending on the property’s elevation, flood zone designation, and structure type.
    • Properties in Zone X or higher-elevation areas of Southport or northern Lynn Haven generally carry lower flood insurance burdens.
    • Buyers should always request a flood zone determination and an elevation certificate before making an offer on any Bay County property.

    We always recommend working with a licensed Florida insurance agent familiar with Bay County before finalizing any purchase decision. Insurance is a material part of your total monthly housing cost here.

    How Does Tyndall AFB Affect the Local Economy and Cost of Living?

    Tyndall Air Force Base is one of the largest employers and economic anchors in Bay County. Its presence creates a stable rental and purchase market, particularly in Springfield, Callaway, and parts of Panama City proper. Military families using VA loans benefit from no down payment requirements and competitive rates, which can make homeownership more accessible in this market even as purchase prices have risen from post-Michael lows.

    The ongoing rebuild and mission expansion at Tyndall has also supported local employment, which helps stabilize the broader Bay County economy and housing demand.

    What Are the Day-to-Day Living Costs Like in Panama City?

    What Do Residents Typically Spend on Everyday Expenses?

    • Dining out: Panama City has a strong local restaurant scene, particularly in St. Andrews and along the beach corridor, with prices that are generally lower than in major metros.
    • Entertainment and recreation: Access to the Gulf of Mexico, North Bay, and state parks like St. Andrews State Park means many recreational activities are free or low-cost.
    • Sales tax: Florida has a 6% state sales tax. Bay County adds a local surtax on top of that for certain purchases, which is typical across Florida counties.
    • No state income tax: Florida does not levy a personal income tax, which is a genuine financial benefit for residents compared to many other states.
    • Property taxes: Bay County property taxes are generally moderate compared to other Florida counties, though assessed values have risen post-Michael as the market recovered.

    Is Panama City a Good Place to Retire on a Fixed Income?

    Retirees considering Panama City will find that the combination of no state income tax, relatively affordable housing outside of premium waterfront areas, access to outdoor recreation, and a lower overall cost of living compared to South Florida makes it a genuinely competitive retirement destination. The key variables to manage carefully are homeowners insurance, flood insurance, and utility costs during summer months. Working with a fee-only financial planner familiar with Florida retirement living is a smart step before committing to a move.

    Frequently Asked Questions About the Cost of Living in Panama City, FL

    Is Panama City, Florida affordable compared to the national average?

    In several important categories, yes. Housing costs in particular tend to be below the national average, and there is no state income tax in Florida. However, property insurance costs in coastal Bay County can be significantly above national norms, which buyers and renters should factor into their budget planning.

    How much does homeowners insurance cost in Panama City, FL?

    Insurance premiums vary widely based on the home’s location, age, construction type, elevation, and flood zone designation. We strongly recommend getting multiple quotes from licensed Florida insurance agents before finalizing a home purchase. Do not rely on national average figures when budgeting for a Bay County home.

    What neighborhoods in Panama City are the most affordable?

    Springfield, Callaway, and parts of Parker tend to offer more affordable entry-level price points. Lynn Haven and Southport skew toward the mid-to-upper range of the local market, while St. Andrews and waterfront properties anywhere in the county command premiums. Your priorities around schools, commute, and flood risk should guide neighborhood selection alongside price.

    Do military families save money living near Tyndall AFB?

    Military families using VA loans can eliminate the down payment requirement and avoid private mortgage insurance, which meaningfully lowers the upfront and monthly cost of homeownership. BAH rates for Tyndall assignments are set to reflect local rental market conditions. Consulting with a VA-experienced lender familiar with Bay County is a recommended first step.

    Are utilities expensive in Panama City, Florida?

    Utility costs are close to state averages but can spike in summer due to air conditioning demand. Most homes in Bay County rely on electric central air systems, and July and August bills can be notably higher than off-season months. Newer construction and homes rebuilt post-Hurricane Michael often include more energy-efficient features that help manage these costs.

    Does Panama City have a state income tax?

    No. Florida does not have a personal state income tax, which is a meaningful financial benefit for residents, particularly retirees living on investment income, Social Security, or pension distributions. This is one of the frequently cited reasons people relocate to Florida from higher-tax states.

    What hidden costs should I watch for when moving to Panama City?

    The two biggest surprises for newcomers tend to be property insurance and flood insurance. Wind mitigation inspections, elevation certificates, and flood zone mapping should all be part of your due diligence before closing on any Bay County home. Working with a local real estate professional and a licensed Florida insurance agent early in the process can help you avoid budget surprises after closing.

    PanamaCityFLHomes.com is built to help you research the local market and make a more confident real estate decision.

    Related Reading

  • First-Time Homebuyer Guide for Panama City FL

    What Do First-Time Homebuyers Need to Know About Panama City, FL?

    Quick Answer: Buying your first home in Panama City, FL means navigating a market shaped by Gulf Coast living, Tyndall AFB proximity, flood zone considerations, and a range of neighborhoods to fit different budgets. Start with mortgage pre-approval, research Bay County neighborhoods carefully, understand flood insurance requirements, and work with local professionals who know the area well.

    Why Is Panama City, FL a Good Place to Buy Your First Home?

    Panama City offers first-time buyers a combination of relative affordability compared to South Florida markets, a strong military and healthcare economy anchored by Tyndall Air Force Base, and a coastal lifestyle that draws retirees, families, and remote workers alike. Bay County has a variety of neighborhoods ranging from quiet suburban streets in Lynn Haven to historic blocks near Downtown Panama City, giving first-time buyers real options at different price points.

    The local economy has continued to recover and grow following Hurricane Michael in 2018, with rebuilt infrastructure, new construction, and updated building codes that make newer homes more resilient than ever. For first-time buyers, this means you can find both move-in-ready resale homes and brand-new construction across Bay County.

    How Does the Panama City Housing Market Work for First-Time Buyers?

    What Are Typical Home Prices in Panama City and Bay County?

    Home prices in Panama City and the surrounding Bay County communities vary significantly by neighborhood and property type. Generally speaking, you will find:

    • Lynn Haven and Callaway: Popular suburban neighborhoods with family-friendly streets, generally more affordable entry-level homes, and strong school options.
    • Springfield and Parker: Some of the most affordable price points in Bay County, making them attractive for first-time buyers on tighter budgets.
    • St. Andrews: A historic waterfront neighborhood with charm and character, though prices can reflect the desirable location.
    • Downtown Panama City: An evolving urban core with mixed-use development, condos, and older homes undergoing renovation.
    • Southport: A more rural, spacious community north of Lynn Haven that appeals to buyers wanting larger lots and a quieter setting.

    Always consult a licensed local real estate agent for current pricing, as the market shifts throughout the year and varies block by block.

    Is It a Good Time to Buy in Panama City in 2026?

    Market conditions in 2026 continue to reflect the broader national landscape of elevated interest rates relative to the historic lows of the early 2020s, but Panama City remains more accessible than many Florida coastal markets. First-time buyers who are financially prepared and pre-approved are generally in a stronger position than those who are not. A local lender familiar with Bay County can help you understand what your purchasing power looks like right now.

    What Loan Programs Are Available for First-Time Homebuyers in Panama City?

    First-time buyers in Bay County have access to several loan program types worth discussing with a licensed mortgage professional:

    • FHA Loans: Lower down payment requirements and more flexible credit guidelines, making them popular for first-time buyers.
    • VA Loans: Available to eligible active-duty military, veterans, and surviving spouses. With Tyndall AFB nearby, many Panama City buyers qualify for VA financing, which typically requires no down payment.
    • USDA Loans: Certain parts of Bay County outside city limits may qualify for USDA rural housing loans with no down payment required.
    • Conventional Loans: For buyers with stronger credit profiles and savings for a down payment.
    • Florida Housing Finance Corporation Programs: The state of Florida offers down payment assistance and first mortgage programs for eligible first-time buyers. Ask a licensed lender about current availability.

    Note: Loan program availability, terms, and eligibility change frequently. Always consult a licensed mortgage professional for guidance specific to your situation.

    What Do First-Time Buyers Near Tyndall AFB Need to Know?

    Tyndall Air Force Base, located just east of Panama City, has been undergoing a major rebuild and modernization following Hurricane Michael. Military families and civilians connected to the base often look at homes in Callaway, Parker, Lynn Haven, and the eastern sections of Panama City for their commute convenience.

    VA loans are especially common in this market. First-time buyers using VA financing should work with a lender experienced in VA transactions and a real estate agent familiar with VA appraisal requirements. Some sellers in Bay County are very familiar with VA offers, which is a real advantage for military buyers shopping here.

    What Should First-Time Buyers Know About Flood Zones in Panama City?

    This is one of the most important local factors for any Panama City homebuyer. Bay County has significant flood zone mapping, and your flood zone designation directly affects your insurance requirements and costs.

    • Properties in FEMA Special Flood Hazard Areas (Zone AE and similar) require flood insurance if you have a federally backed mortgage.
    • Even homes outside mandatory flood zones may benefit from flood insurance, given the area’s storm history.
    • Flood insurance in Florida is purchased separately from your homeowner’s insurance policy.
    • Always ask your real estate agent to provide the flood zone designation of any home you are seriously considering, and request an elevation certificate if one is available.
    • Consult a licensed insurance professional for current flood insurance quotes before making an offer — costs can vary dramatically based on a home’s elevation and zone.

    Understanding flood insurance costs before you fall in love with a property can prevent budget surprises at closing.

    What Steps Should a First-Time Homebuyer Take in Panama City?

    Step 1: Get Pre-Approved by a Local Lender

    Before you browse listings seriously, get pre-approved by a lender who knows the Bay County market. A pre-approval letter tells sellers you are a serious buyer and gives you a realistic budget to work with.

    Step 2: Research Neighborhoods That Fit Your Life

    Think about your commute, school needs, flood zone tolerance, and lifestyle preferences. Lynn Haven and Callaway tend to suit families. Springfield and Parker offer value. St. Andrews offers walkable coastal character. Southport suits those wanting space and quiet.

    Step 3: Work With a Local Real Estate Agent

    A Panama City area agent understands local flood zones, HOA situations, post-hurricane rebuild considerations, and neighborhood nuances that out-of-area agents may miss.

    Step 4: Budget for Florida-Specific Costs

    Beyond your mortgage, budget for homeowner’s insurance, flood insurance (if applicable), wind coverage, property taxes, and potential HOA fees. Florida insurance costs have risen in recent years, so get quotes early in the process.

    Step 5: Get a Thorough Home Inspection

    In a coastal market with a major hurricane in recent history, a detailed home inspection is non-negotiable. Look for a licensed inspector with experience in Gulf Coast properties who can evaluate roofing, windows, and any storm-related repairs.

    FAQ: First-Time Homebuyer Questions for Panama City, FL

    Do I need a large down payment to buy a home in Panama City?

    Not necessarily. FHA loans allow as little as 3.5% down, and VA and USDA loans may require no down payment for eligible buyers. Florida Housing programs may also offer down payment assistance. Talk to a licensed lender to find the right fit for your financial situation.

    Is flood insurance required for all homes in Panama City?

    Flood insurance is required by lenders for homes in designated Special Flood Hazard Areas. However, many homes in Bay County fall outside mandatory zones. Even so, many buyers choose to purchase optional flood coverage given the area’s hurricane history. Consult a licensed insurance professional for your specific address.

    What are closing costs like in Bay County, FL?

    Closing costs in Florida typically include title insurance, lender fees, prepaid insurance and taxes, and other transaction costs. They generally range from 2% to 5% of the purchase price, though your specific costs depend on your loan type and negotiated terms. Ask your lender for a Loan Estimate early in the process.

    Are there good schools near the neighborhoods in Panama City?

    Bay County has a mix of public and charter school options across its communities. Lynn Haven and Callaway are frequently cited by families as having convenient school access. Research specific school zones through the Bay District Schools website and visit campuses when possible.

    How long does the homebuying process take in Panama City?

    From accepted offer to closing, most transactions take 30 to 45 days, though this can vary based on loan type, inspection findings, and title work. VA loans sometimes take slightly longer due to appraisal scheduling. Your agent and lender can give you a realistic timeline based on current conditions.

    What should I know about homeowner’s insurance costs in Panama City?

    Florida’s insurance market has experienced significant rate increases in recent years, and Bay County’s coastal location means wind coverage is a key factor. Get insurance quotes before making an offer so you understand the full cost of ownership. Work with a licensed insurance agent familiar with Bay County.

    Can military buyers get help buying a first home near Tyndall AFB?

    Yes. Eligible active-duty service members, veterans, and surviving spouses can use VA loan benefits, which typically include no down payment and no private mortgage insurance. Many local lenders and agents in the Panama City area specialize in VA transactions and understand the unique timeline needs of military families.

    PanamaCityFLHomes.com is built to help you research the local market and make a more confident real estate decision.

    Related Reading

  • Panama City FL Market Update: What Buyers and Sellers Need to Know Right Now

    Panama City FL Market Update: What Buyers and Sellers Need to Know Right Now

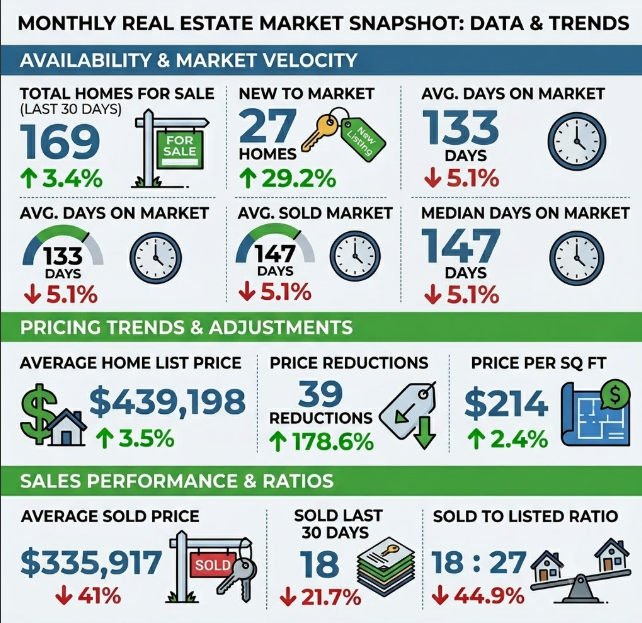
    The latest Panama City, FL real estate data is in — and it tells a very different story depending on which side of the transaction you’re on. Here’s what the numbers mean for buyers and sellers right now.


    For Buyers: An Increasing Advantage

    This market is turning highly favorable for buyers, offering more leverage and less pressure than before.

    More Options and Less Urgency

    With new listings up 29.2% and homes sitting on the market for an average of 133 days, you don’t have to rush into a decision. You have more inventory to choose from and time to weigh your options.

    Stronger Negotiating Power

    The massive 178.6% spike in price reductions shows that sellers are getting anxious. You have a distinct advantage to negotiate lower purchase prices, closing cost credits, or repair allowances.

    A Discount Opportunity

    The gap between the average list price ($439,198) and the average sold price ($335,917) indicates that homes are either selling well below asking price, or the properties actually closing are on the more affordable end of the spectrum. Either way, buyers are winning.


    For Sellers: A Reality Check

    Sellers are facing a much tougher, more competitive environment where aspirational pricing is no longer working.

    Price it Right from Day One

    While the average list price is up, the average sold price has plummeted by 41%. Overpricing your home initially will likely just land you in the “price reduction” category, where cuts are currently spiking at nearly 179%. Strategic, realistic pricing from the start is your best weapon.

    Expect a Longer Wait

    With an average of 133 days on market, you need to prepare for your home to sit for several months before finding a buyer. Patience and deep flexibility on terms will be required.

    Stiffer Competition

    New inventory is flooding in faster than it is selling — new listings are up nearly 30%, but total sales are down over 21%. Your home needs to stand out in terms of condition, presentation, and realistic pricing to capture the fewer buyers actively closing deals.


    Key Market Stats at a Glance

    • Total Homes for Sale: 169  (up 3.4%)
    • New Listings (Last 30 Days): 27  (up 29.2%)
    • Avg. Days on Market: 133 days  (down 5.1%)
    • Average List Price: $439,198  (up 3.5%)
    • Average Sold Price: $335,917  (down 41%)
    • Price Reductions: 39  (up 178.6%)
    • Price Per Sq Ft: $214  (up 2.4%)
    • Homes Sold Last 30 Days: 18  (down 21.7%)
    • Sold-to-Listed Ratio: 18:27  (down 44.9%)

    Bottom Line

    The Panama City, FL housing market has shifted decisively in favor of buyers. If you’re looking to purchase, now is an excellent time to explore your options with confidence. If you’re selling, a strategic approach — competitive pricing, excellent presentation, and realistic expectations — is more important than ever.

    Have questions about what this means for your specific situation? Reach out today — I’m here to help you navigate this market with clarity and confidence.

    Related Reading

  • Beyond the Beach: The Investor’s Guide to Long-Term Rentals in Bay County, FL

    Beyond the Beach: The Investor’s Guide to Long-Term Rentals in Bay County, FL

    When most people think of real estate investing in Panama City, Florida, their minds jump straight to vacation rentals and beachfront condos. But savvy investors are quietly building wealth through a different strategy — one that delivers predictable cash flow, lower turnover, and a tenant pool that practically manages itself: long-term rentals in Bay County, FL.

    From the military families stationed at Tyndall Air Force Base to the workforce professionals driving Bay County’s post-hurricane economic revival, demand for quality long-term rental housing is strong and growing. This guide breaks down everything you need to know to evaluate, finance, and manage a long-term rental investment in the Panama City area.

    Definition: Long-Term Rental
    A residential rental property leased under a standard lease agreement for a term of 12 months or more. Unlike short-term or vacation rentals, long-term rentals are governed by Florida Statute Chapter 83, Part II (the Florida Residential Landlord and Tenant Act), and are not subject to local short-term rental ordinances or tourist development taxes.

    Why Bay County Is a Strong Long-Term Rental Market

    Bay County’s rental market is anchored by two powerful, overlapping demand drivers that insulate it from the volatility seen in purely tourism-dependent markets.

    The Tyndall AFB Effect

    Tyndall Air Force Base is the single most important factor for long-term rental investors in the Panama City area. The base’s ongoing reconstruction following Hurricane Michael has brought thousands of military personnel and contractors back to Bay County — and the waitlist for on-base housing can stretch from several months to over a year. That means the majority of military families must rent off-base, creating a consistent, reliable pipeline of tenants for local landlords.

    What makes military tenants especially attractive is the Basic Allowance for Housing (BAH) — a non-taxable monthly stipend the Department of Defense pays to service members to cover off-base housing costs. The 2026 BAH rates for the Panama City Military Housing Area (MHA FL063) provide a clear benchmark for setting competitive rents:

    • E-5 (Enlisted, with dependents): $2,163/month
    • E-7 (Enlisted, with dependents): $2,538/month
    • O-3 (Officer, with dependents): $2,709/month
    • O-5 (Officer, with dependents): $3,060/month

    Because BAH is paid directly to the service member and is specifically designated for housing, military tenants are among the most financially reliable renters in any market. Check for updates: BAH rates are adjusted annually by the Department of Defense, typically announced in December for the following year.

    Broader Market Fundamentals

    Beyond the base, Bay County benefits from Florida’s continued status as a high-migration state. The statewide average rent is approximately $1,900/month as of early 2026, and while the market has normalized from pandemic-era peaks, rents remain significantly above pre-2020 levels. Single-family rentals — the most common investment vehicle in Bay County — continue to experience tighter vacancy rates than the multifamily sector, which has seen more new construction pressure statewide.

    The Bay County Neighborhood Investor Filter

    Not all Panama City neighborhoods are created equal for long-term rental investors. Here is a practical framework — the Bay County Investor Neighborhood Filter — to evaluate each area across four dimensions: tenant demand, school quality, flood risk, and entry price point.

    Callaway: The Military Investor’s Sweet Spot

    Callaway sits closest to Tyndall AFB, making it the top choice for investors targeting military tenants. Post-hurricane rebuilding has introduced significant new construction, and the predictable occupancy driven by the base distinguishes it from more volatile, tourism-dependent markets. Best for: Investors prioritizing occupancy stability and BAH-aligned rents.

    Lynn Haven: Premium Family Rentals

    Lynn Haven is widely considered the premier location for family-oriented long-term rentals in Bay County. Top-rated schools, well-maintained parks, and a strong community identity attract stable, long-term tenants — including military officers and civilian professionals. Expect higher purchase prices, but also stronger appreciation potential and lower turnover. Best for: Investors prioritizing appreciation and tenant quality over maximum cash flow.

    Springfield: The Cash Flow Entry Point

    Adjacent to Callaway, Springfield offers lower-cost entry points that appeal to junior enlisted personnel (E-1 through E-4). Lower purchase prices can translate to stronger cash-on-cash returns, though investors should conduct careful due diligence on property condition and flood zone classification. Best for: Investors focused on maximizing cash-on-cash return with a smaller initial capital outlay.

    Parker: Proximity and Value

    Parker offers convenient access to Tyndall AFB and is popular among military personnel and local workers. It represents a middle ground between Callaway’s premium and Springfield’s entry-level pricing. Best for: Investors seeking a balance of proximity to the base and value pricing.

    Downtown Panama City: Redevelopment Upside

    Downtown Panama City is undergoing significant infrastructure improvements and redevelopment, creating opportunities in small multifamily properties and workforce housing. However, investors must conduct thorough due diligence on flood zone classifications — many downtown parcels fall in high-risk zones — and factor in the associated insurance costs before committing. Best for: Experienced investors comfortable with higher complexity and longer value-realization timelines.

    Running the Numbers: A Bay County Cash Flow Framework

    Before making any offer, run a complete cash flow analysis. Do not rely on pro forma numbers from sellers — verify every expense independently. Here is the four-step framework:

    1. Effective Gross Income (EGI): Start with your annual gross potential rent, then subtract a vacancy allowance. For a strong Bay County market, use 5–8% vacancy for military-adjacent properties; use 8–10% for other areas.
    2. Net Operating Income (NOI): Subtract all operating expenses from EGI. Key expenses include: property taxes, hazard insurance, flood insurance (mandatory — see below), property management fees (budget 8–12% of collected rent), and maintenance/repairs (budget 5–10% of rent).
    3. Pre-Tax Cash Flow: Subtract your annual mortgage payments (principal + interest + taxes + insurance, or PITI) from NOI.
    4. Net Free Cash Flow: Subtract a Capital Expenditure (CapEx) reserve — budget 5–10% of EGI annually — for major replacements like roofs, HVAC systems, and appliances. This is your true profit.

    Key metrics to calculate: Cash-on-Cash Return (Annual Cash Flow ÷ Total Cash Invested) and Cap Rate (NOI ÷ Property Value). A healthy cash-on-cash return for Bay County long-term rentals typically falls in the 5–9% range, depending on neighborhood and financing structure.

    Financing Your Bay County Investment Property

    Investors have two primary financing routes, each with distinct advantages:

    Conventional Investment Loans

    Underwritten based on your personal financial profile. Requires income verification (W-2s or tax returns), a debt-to-income ratio below 45–50%, a minimum credit score of 620 (780+ for best rates), and a down payment of 15–25%. Lenders typically cap financing at ten properties.

    DSCR Loans (Debt Service Coverage Ratio)

    Underwritten based on the property’s income, not your personal income. The key metric is the DSCR: monthly rental income divided by the monthly mortgage payment (PITI). Most lenders require a ratio of 1.0x to 1.25x. No personal income verification is required, loans can close in an LLC’s name (providing asset protection), and there is no cap on the number of properties financed. Down payments are typically 20–25%. As of this writing, DSCR loans are widely available in Florida — check for updates on rate and qualification trends.

    Definition: DSCR (Debt Service Coverage Ratio)
    A metric used by lenders to evaluate investment property loans. It is calculated as: Monthly Gross Rental Income ÷ Monthly PITI Payment. A DSCR of 1.0 means the property’s rent exactly covers the mortgage payment. A ratio above 1.0 indicates positive cash flow; below 1.0 indicates a shortfall. Most lenders require a minimum DSCR of 1.0x to 1.25x for loan approval.

    Florida Landlord Law: What Bay County Investors Must Know

    Florida’s landlord-tenant law (Chapter 83, Part II) is generally considered landlord-friendly, but strict compliance is non-negotiable. Key rules for Bay County investors:

    • Security Deposits: Must be held in a separate Florida bank account (interest-bearing or non-interest-bearing) or covered by a surety bond. You must notify the tenant in writing within 30 days of where the deposit is held. To make a claim against the deposit, you must send a written notice by certified mail within 30 days of the tenant vacating — missing this deadline forfeits your right to claim.
    • Eviction for Non-Payment: Serve a 3-Day “Pay or Vacate” Notice (excluding weekends and legal holidays) stating the exact rent owed. If the tenant does not pay or vacate, you may file for eviction in Bay County Circuit Court. Uncontested evictions typically resolve in 2–4 weeks.
    • Notice Updates (As of July 1, 2025): Landlords and tenants may now agree in writing to use email for official notices, streamlining communication. Check for updates: Florida landlord-tenant law is subject to legislative changes each session.
    • Required Disclosures: All leases must include a radon gas warning. Properties built before 1978 require a lead-based paint disclosure.

    The Coastal Risk Factor: Flood Zones and Insurance

    No Bay County investment analysis is complete without a clear-eyed look at flood and hurricane risk. Standard homeowners insurance does not cover flood damage — a separate flood insurance policy is essential.

    Annual flood insurance cost estimates by zone:

    • Moderate-Risk (Zone X): $800–$2,000/year
    • High-Risk (Zone AE): $2,000–$10,000/year
    • High-Risk Coastal (Zone VE): $5,000–$20,000+/year

    Always verify a property’s flood zone designation and obtain a flood insurance quote before making an offer — not after. Also budget for Florida’s separate hurricane deductible, which is typically 2–10% of the dwelling’s insured value and must be paid out-of-pocket before wind damage coverage kicks in. Check for updates: Florida’s insurance market has shown signs of stabilization in 2026 following legislative reforms, but rates remain elevated — verify current quotes with a licensed Florida insurance agent.

    Key Takeaways

    • Tyndall AFB is your anchor: Military BAH rates set a reliable rent benchmark, and the on-base housing waitlist ensures a steady off-base tenant pipeline. Target Callaway and Parker for maximum proximity to the base.
    • Match neighborhood to strategy: Lynn Haven for appreciation and tenant quality; Callaway/Parker for military demand; Springfield for cash flow entry points; Downtown for experienced investors seeking redevelopment upside.
    • Run a full four-step cash flow analysis: Include flood insurance, a CapEx reserve, and property management fees — these are the expenses most investors underestimate.
    • DSCR loans unlock scale: If you plan to build a portfolio, DSCR loans allow LLC ownership, no income verification, and no property cap — ideal for Bay County’s investment-friendly market.
    • Flood zone due diligence is non-negotiable: Always verify the flood zone and get an insurance quote before making an offer. A Zone AE property can carry $5,000–$10,000/year in flood insurance alone.
    • Know the 30-day deposit rule: Missing Florida’s 30-day deadline to claim a security deposit forfeits your right to withhold any portion — set a calendar reminder the day a tenant vacates.

    Long-term rentals in Bay County, FL offer a compelling combination of stable military-driven demand, a landlord-friendly legal environment, and a market that is still accessible compared to Florida’s larger metros. With the right neighborhood selection, a disciplined cash flow analysis, and a clear understanding of coastal risk, investors can build a durable, income-producing portfolio in one of the Panhandle’s most resilient markets.

    Last updated: May 15, 2026. Real estate markets, BAH rates, insurance costs, and Florida statutes change regularly. Consult a licensed Florida real estate agent, attorney, and insurance professional before making investment decisions.

    Related Reading

  • Don’t Get Soaked: A First-Time Buyer’s Guide to Flood Zones in Panama City, FL

    Don’t Get Soaked: A First-Time Buyer’s Guide to Flood Zones in Panama City, FL

    Last updated: May 2026. Check for updates: FEMA flood map designations and insurance rates change periodically — verify current zone status and premium quotes before closing.

    Buying your first home in Panama City, FL is one of the most exciting decisions you’ll ever make. The Gulf Coast lifestyle, the bayous, the beaches, the community — it’s easy to fall in love fast. But before you make an offer on that charming bungalow near St. Andrews Bay or a newer build in Breakfast Point, there’s one critical piece of due diligence that first-time buyers often overlook: understanding the property’s flood zone designation.

    In a coastal market like Panama City, flood zone status isn’t a footnote — it can determine whether your mortgage is approved, how much your insurance costs, and whether your home retains its value after a major storm. This guide breaks it all down in plain language, with a practical checklist tailored specifically to Bay County buyers.

    Definition: Special Flood Hazard Area (SFHA)
    A FEMA-designated zone with at least a 1% annual chance of flooding — commonly called the “100-year floodplain.” Homes in SFHAs with federally backed mortgages are required by law to carry flood insurance. Over a 30-year mortgage, a home in an SFHA has roughly a 1-in-4 chance of experiencing a flood event.

    Why Flood Zones Matter More in Panama City Than Almost Anywhere Else

    Panama City sits on a relatively flat coastal plain bordered by St. Andrews Bay, North Bay, and dozens of bayous and tidal creeks. That geography is beautiful — and it also means water has many pathways into neighborhoods during storms. The region’s vulnerability became undeniable on October 10, 2018, when Hurricane Michael made landfall as a catastrophic Category 5 storm. Storm surge flooded the main strip, neighborhoods near the bay were inundated, and Tyndall Air Force Base suffered approximately $5 billion in damage.

    For first-time buyers, this history is not meant to discourage — it’s meant to inform. Panama City has rebuilt stronger, and thousands of families happily call it home. But going in with eyes open about flood risk is the mark of a smart buyer.

    FEMA Flood Zone Categories: Decoding the Alphabet

    FEMA creates Flood Insurance Rate Maps (FIRMs) that divide every community into flood zones. Here’s what the key designations mean for Panama City buyers:

    High-Risk Zones (Flood Insurance Mandatory with Federal Mortgage)

    • Zone VE (Coastal High Hazard): The highest-risk designation. These properties face a 1% annual flood chance plus the added danger of storm-driven waves. Homes must be built on pilings to a specified Base Flood Elevation (BFE). Common along Panama City Beach’s Gulf-front and bay-front areas.
    • Zone AE: A 1% annual flood chance with a determined BFE. Typically covers inland areas near bayous, rivers, and low-lying neighborhoods. Much of Panama City’s older residential stock near North Bay and the bayou corridors falls here.
    • Zone A: Same 1% annual risk as AE, but without a detailed BFE study. Less common but still triggers mandatory insurance requirements.
    • Zone AO / AH: Shallow flooding zones — typically 1 to 3 feet of sheet-flow or ponding water. Found in some low-lying inland areas of Bay County.

    Moderate-to-Low Risk Zones (Insurance Optional but Recommended)

    • Zone X (Shaded) / Zone B: Between the 100-year and 500-year floodplain. Moderate risk — flood insurance is not required but is strongly advisable. Many newer subdivisions in areas like Callaway and parts of Lynn Haven fall here.
    • Zone X (Unshaded) / Zone C: Minimal flood hazard, outside the 500-year floodplain. Lowest risk, but flooding from drainage issues or extreme rainfall is still possible.

    Definition: Base Flood Elevation (BFE)
    The height (in feet above sea level) that floodwaters are expected to reach during a “base flood” (1% annual chance event). Your home’s lowest floor elevation relative to the BFE is the single biggest factor in determining your flood insurance premium. A home built 2 feet above BFE can cost dramatically less to insure than one built at or below it. Check for updates: BFEs are revised when FEMA updates flood maps — always verify the current BFE for any property you’re considering.

    Bay County’s 2024 Flood Map Update: What Changed

    Flood maps are not static documents. Bay County adopted new, federally mandated FIRMs that became effective August 16, 2024 — the first major update since 2010. This is critical context for any buyer in Panama City right now.

    Key changes from the 2024 remapping include:

    • Zone reclassifications: Some properties previously in low-risk Zone X were moved into high-risk AE zones, triggering new mandatory insurance requirements for existing homeowners.
    • Higher BFEs: In some areas, the required elevation was raised, meaning new construction or substantial renovations must be built higher than before.
    • Expanded flood hazard areas: Flood risk expanded further inland in certain parts of Panama City, particularly on the western side near Gulf Coast State College.

    If you’re looking at a home built before 2024, its flood zone status on the seller’s disclosure may be outdated. Always verify the current designation yourself using the tools below.

    How to Look Up Any Property’s Flood Zone in Panama City

    You don’t need to hire anyone to do an initial flood zone check — these tools are free and publicly available:

    1. FEMA Flood Map Service Center (msc.fema.gov): Enter the property address to pull up the official FIRM. Use the “FIRMette” tool to generate a printable map panel for the specific property.
    2. City of Panama City Public Forerunner Flood Website (panamacity.gov): Panama City offers a user-friendly local portal where you can look up a property’s flood zone, BFE, and compliance information by address.
    3. Bay County Flood Zone Information (baycountyfl.gov): Bay County’s website provides additional resources including CRS (Community Rating System) information, which can affect your NFIP insurance discount.

    Pro tip: Run the address through both the FEMA tool and the local city/county portal. Discrepancies are rare but possible, and local portals sometimes reflect the most current adopted maps faster.

    The Elevation Certificate: Your Secret Weapon for Lower Insurance Costs

    An Elevation Certificate (EC) is a document prepared by a licensed Florida surveyor, engineer, or architect that records the precise elevation of a home’s lowest floor relative to the BFE. It’s one of the most valuable documents a seller can hand over at closing — and one of the most overlooked by first-time buyers.

    Here’s why it matters:

    • Insurance pricing: Insurance companies use the EC to set accurate flood premiums. A home elevated 2 feet above BFE in Zone AE can cost hundreds of dollars less per year to insure than one at BFE.
    • LOMA applications: If a property’s land is naturally above the BFE but was mapped into an SFHA, the owner can use an EC to apply for a Letter of Map Amendment (LOMA) — potentially removing the mandatory insurance requirement entirely.
    • Building compliance: ECs confirm that a structure meets current elevation standards, which matters for resale value and future renovations.

    Always ask the seller: “Do you have a current Elevation Certificate?” If not, budget $300–$600 to have one prepared by a licensed Florida surveyor. It often pays for itself in the first year of insurance savings.

    Flood Insurance Costs in Bay County: What to Budget

    Standard homeowners insurance policies do not cover flood damage. You need a separate flood insurance policy, either through FEMA’s National Flood Insurance Program (NFIP) or a private carrier.

    Average annual NFIP premiums in Bay County range from approximately $230 to $485 — notably lower than Florida’s statewide average of $800–$900. However, your actual premium depends on:

    • Your flood zone (VE is significantly more expensive than AE or X)
    • Your home’s elevation relative to BFE (the higher above BFE, the lower the cost)
    • The age and construction type of the home
    • Your chosen coverage amount and deductible

    Private flood insurance is increasingly competitive in Florida and may offer broader coverage or lower rates than NFIP for some properties. Always get quotes from both sources. Check for updates: Florida’s private flood insurance market is evolving rapidly — rates and carrier availability change frequently.

    How Flood Zones Affect Your Mortgage

    If you’re financing your purchase with an FHA, VA, conventional (Fannie Mae/Freddie Mac), or USDA loan — which covers the vast majority of first-time buyers — your lender is federally required to:

    • Perform a flood zone determination before closing
    • Require proof of flood insurance if the property is in an SFHA (A or V zone)
    • Monitor the property’s flood zone status for the life of the loan

    If FEMA remaps your property into a high-risk zone after you close, your lender will notify you that flood insurance is now required. Failure to obtain it results in force-placed insurance — a lender-purchased policy that is typically far more expensive and offers less coverage than what you’d buy yourself.

    The Panama City Coastal Risk Filter: A First-Time Buyer’s Checklist

    Use this framework before making any offer on a Panama City property. Think of it as your personal flood risk due-diligence filter:

    • ☐ Zone Check: Look up the property on FEMA’s Flood Map Service Center and Panama City’s local flood portal. Identify the zone (VE, AE, X, etc.).
    • ☐ Map Currency: Confirm you’re looking at the maps effective August 16, 2024 or later — not pre-2024 data.
    • ☐ Elevation Certificate: Request the seller’s EC. If unavailable, get a surveyor quote before closing.
    • ☐ Insurance Quotes: Get NFIP and private flood insurance quotes before making your final offer — factor the annual premium into your monthly budget.
    • ☐ Flood History: Ask the seller directly about past flooding or water intrusion, especially from Hurricane Michael (2018). Review the seller’s disclosure carefully.
    • ☐ BFE Comparison: If in an AE or VE zone, confirm how the home’s lowest floor elevation compares to the BFE. Above BFE = lower insurance costs and better resilience.
    • ☐ Neighborhood Context: Research whether the surrounding neighborhood (e.g., near North Bay, a bayou corridor, or Gulf-front) has a history of storm surge or drainage flooding.
    • ☐ X Zone Reality Check: Even in Zone X, consider a flood policy. FEMA data shows more than 25% of flood claims come from outside high-risk zones.

    Key Takeaways

    • Panama City’s coastal geography and Hurricane Michael history make flood zone research non-negotiable for first-time buyers.
    • FEMA flood zones range from high-risk VE and AE (mandatory insurance with federal mortgages) to lower-risk Zone X (insurance optional but recommended).
    • Bay County adopted updated flood maps in August 2024 — always verify current zone status, not what’s on an older seller’s disclosure.
    • An Elevation Certificate is one of the most valuable documents a seller can provide; it directly impacts your insurance premium and can save you hundreds per year.
    • Average NFIP flood insurance in Bay County runs $230–$485/year — lower than the Florida average, but still a real budget line item to plan for.
    • Use the Panama City Coastal Risk Filter checklist above before making any offer to ensure you’ve covered every flood-related angle.
    • Even in low-risk Zone X, flood insurance is worth considering — standard homeowners policies never cover flood damage.

    Understanding flood risk doesn’t mean avoiding Panama City — it means buying here with confidence. The buyers who do their homework on flood zones, elevation certificates, and insurance costs are the ones who close without surprises and build lasting equity in one of Florida’s most desirable coastal communities.


    This post is for informational purposes only and does not constitute legal, financial, or insurance advice. Flood zone designations, insurance rates, and regulations are subject to change. Always consult a licensed Florida real estate professional, insurance agent, and lender for guidance specific to your situation. Last updated: May 2026.

    Related Reading

  • Beyond the School Ratings: A Family’s Complete Guide to Lynn Haven vs. Breakfast Point in Panama City FL

    Beyond the School Ratings: A Family’s Complete Guide to Lynn Haven vs. Breakfast Point in Panama City FL

    Last updated: May 2026. Check for updates on school zoning, HOA fees, and flood map designations annually.

    When families relocate to the Panama City, Florida area, two neighborhoods consistently rise to the top of the shortlist: Lynn Haven and Breakfast Point. Both offer strong schools, family-friendly amenities, and access to the Gulf Coast lifestyle that makes Bay County one of Florida’s most desirable places to raise children. But they are fundamentally different places to live — and choosing the wrong one can mean years of frustration.

    This guide goes beyond school ratings to give you a complete, honest comparison: home prices, flood risk, HOA governance, commute realities, and the lifestyle trade-offs that matter most to families buying a home in Panama City FL in 2026.

    Key Takeaways

    • Lynn Haven offers more affordable entry prices (~$350K median) and an established community feel; Breakfast Point offers modern construction and curated amenities starting around $433K.
    • Both areas carry significant hurricane and flood risk — but Breakfast Point’s newer homes are built to more stringent post-storm codes, which can affect insurance costs.
    • Lynn Haven’s school advantage is charter school access (Bay Haven Charter Academy, 8/10); Breakfast Point’s is guaranteed zoning for Breakfast Point Academy (K–8) and Arnold High School.
    • Lynn Haven has no community-wide HOA; Breakfast Point’s mandatory HOA governs aesthetics and shared amenities.
    • Military families at Tyndall AFB will find Lynn Haven’s commute (30–35 min) far more predictable than Breakfast Point’s (up to 60 min in tourist season).
    • Use the Panama City Family Neighborhood Filter framework below to score each community against your priorities before making an offer.

    Definition: Bay District Schools — The public school system serving all of Bay County, Florida, including Panama City, Lynn Haven, and Panama City Beach. School zone assignments are address-specific; always verify your exact zoning at the district’s official “Find My School” tool before purchasing. (Check for updates: zoning boundaries can shift between school years.)

    Community Character at a Glance

    Lynn Haven: Established Suburban City with a Coastal Edge

    Lynn Haven sits north of Panama City along North Bay, offering a genuine small-city identity — its own mayor, parks department, and community events calendar. The housing stock is diverse: roughly 46% of homes were built between 1970 and 1999, with 43% constructed in 2000 or later. Median age is 37, median household income is ~$83,093, and 69% of households are family households. The city is largely car-dependent but has a notable 7.8% remote-work rate, making it popular with professionals seeking suburban space.

    Breakfast Point: Master-Planned for the Modern Family

    Breakfast Point is a purpose-built community in Panama City Beach where every home is new or recent construction. Its signature amenity is direct access to Gayle’s Trails, a paved trail network spanning 30+ miles connecting residents to parks and the Panama City Beach Sports Complex. The lifestyle is deliberately active and family-centric — but the community sits within a major tourist destination, meaning US Highway 98 traffic is a real daily-life factor from spring through fall.

    Home Prices and the 2026 Market

    As of early 2026, Lynn Haven’s median home sale price was approximately $350,000 (up 19.3% year-over-year), with a median price per square foot of $193 and an average of 44 days on market. The variety of housing types means buyers can find options both below and above the median.

    Breakfast Point is a premium market. New builds from Harris Doyle Homes, Fischer Homes, and Truland Homes start around $433,000 for ~1,600 sq. ft. and climb past $660,000 for larger floor plans. Builders are currently offering incentives — closing cost credits and rate buydowns — to attract buyers in the rebalancing Florida market. (Check for updates: builder incentive programs change frequently.)

    Schools: Charter Access vs. Guaranteed Zoning

    Lynn Haven

    Zoned public elementary schools have mixed ratings, but the area’s charter schools are a genuine differentiator. Bay Haven Charter Academy (K–5) is rated 8/10 by NeighborhoodScout, with student proficiency well above state averages in reading and math. North Bay Haven Charter Academy Elementary is also highly regarded. Note: Florida charter schools are tuition-free but require an application — popular charters often have waitlists. (Check for updates: charter enrollment policies change annually.)

    Breakfast Point

    Breakfast Point’s zoning is a key selling point. The community is zoned for Breakfast Point Academy (K–8), located within the neighborhood itself, and Arnold High School, both consistently strong performers in Bay District Schools. Your address guarantees enrollment — no application or waitlist required. Always verify current zoning using the specific property address before making an offer.

    The Coastal Risk Filter: Flood Zones, Wind, and Insurance

    No Panama City FL neighborhood guide is complete without an honest assessment of environmental risk. Hurricane Michael’s 2018 Category 5 landfall reshaped how buyers, insurers, and lenders think about Bay County real estate.

    Definition: Flood Zone AE — A high-risk FEMA flood zone with a 1% or greater annual chance of flooding (the “100-year floodplain”). Properties in Flood Zone AE typically require mandatory flood insurance with a federally backed mortgage. Flood insurance is purchased separately from standard homeowners insurance in Florida. Always obtain an elevation certificate for any property in or near a flood zone. (Check for updates: FEMA remapping can change a property’s zone designation.)

    Lynn Haven: Significant and Growing Risk

    Risk Factor™ analysis shows 50% of Lynn Haven properties face severe flood impact risk over the next 30 years, and 100% of properties are at extreme wind risk (projected gusts up to 170 mph in 30 years). In October 2024, FEMA updated Bay County’s flood maps, expanding designated flood zones. Bay County officials strongly advise all residents to carry flood insurance regardless of official zone designation. Buyers of older Lynn Haven homes must request wind mitigation reports, elevation certificates, and current insurance quotes before making an offer. (Check for updates: FEMA flood map revisions are ongoing.)

    Breakfast Point: Newer Codes, Same Geography

    Breakfast Point shares the same Gulf Coast hurricane exposure as the rest of Bay County. The critical difference is its building stock: every home was constructed under modern Florida Building Code standards — significantly strengthened after Hurricane Andrew and refined further after subsequent storms — addressing wind resistance, roof-to-wall connections, and elevation requirements. This can result in more favorable wind mitigation credits and potentially lower insurance premiums compared to older homes. All Breakfast Point buyers should obtain insurance quotes before going under contract. (Check for updates: Florida’s insurance market is in active flux.)

    The Panama City Family Neighborhood Filter

    Score each factor 1–5 based on importance to your family, then tally which community wins more of your high-priority dimensions:

    1. Budget flexibility — Lynn Haven wins on affordability.
    2. School certainty — Breakfast Point wins for guaranteed zoning; Lynn Haven wins if charter quality suffices.
    3. New construction preference — Breakfast Point wins decisively.
    4. Established community character — Lynn Haven wins.
    5. Trail and outdoor amenities — Breakfast Point wins with Gayle’s Trails.
    6. Commute to Tyndall AFB — Lynn Haven wins (30–35 min vs. up to 60 min).
    7. HOA-free living — Lynn Haven wins; Breakfast Point has a mandatory HOA.
    8. Insurance/risk management — Breakfast Point’s newer construction may offer a modest advantage; both require serious planning.

    Which Neighborhood Is Right for Your Family?

    Choose Lynn Haven if you:

    • Want a more affordable entry point into Bay County homeownership
    • Value an established, diverse community with a genuine small-city identity
    • Are comfortable navigating charter school applications for the best educational options
    • Prefer life without a mandatory HOA
    • Have a regular commute to Tyndall AFB or downtown Panama City

    Choose Breakfast Point if you:

    • Prefer new construction with modern energy efficiency and building code compliance
    • Want guaranteed zoning for highly-regarded schools without a waitlist
    • Value integrated trail systems and curated outdoor amenities
    • Are comfortable with HOA governance and its associated fees
    • Work remotely or have a flexible commute unaffected by tourist-season traffic

    This post reflects market conditions and regulatory information as of May 2026. Florida real estate regulations, school zoning, flood maps, HOA rules, and insurance markets change frequently. Always verify current information with a licensed Florida real estate agent, Bay District Schools, Bay County Property Appraiser, and your insurance provider before making a purchase decision.

    Related Reading

  • Buying in Bay County: How to Maximize Your VA Loan Benefits in 2026


    Buying in Bay County: How to Maximize Your VA Loan Benefits in 2026

    Buying in Bay County: How to Maximize Your VA Loan Benefits in 2026

    Last updated: April 2026. Check for updates on VA funding fee rates and BAH figures annually, as these are set by the Department of Defense and may change each calendar year.

    If you are an active-duty service member, veteran, or eligible surviving spouse looking to buy a home in Panama City, FL, you have access to one of the most powerful mortgage tools in existence: the VA home loan. In Bay County — home to the rapidly rebuilding Tyndall Air Force Base — understanding how to fully leverage this benefit can mean the difference between renting indefinitely and owning a home with zero down payment and no monthly mortgage insurance.

    This guide walks you through everything you need to know about using a VA loan in the Panama City market in 2026, including local considerations that most generic guides miss.


    Key Takeaways

    • Veterans and active-duty service members with full VA entitlement face no VA-imposed loan limit in 2026 — you can borrow as much as a lender will approve with zero down payment.
    • Bay County’s 2026 conforming loan limit is $832,750, which matters only if you have partial entitlement (e.g., an existing VA loan).
    • The VA funding fee for a first-time, zero-down purchase is 2.15% — but veterans receiving disability compensation are fully exempt.
    • Tyndall AFB’s ongoing rebuild is a major economic driver; BAH income from the base can be used to qualify for a VA loan.
    • Coastal properties in Panama City may require mandatory flood insurance if located in a FEMA Special Flood Hazard Area (SFHA).
    • The VA appraisal checks both value and property condition — older or storm-damaged homes near the coast may require repairs before closing.

    What Makes the VA Loan So Powerful in 2026?

    Three core benefits set the VA loan apart from every other mortgage product on the market:

    1. No Down Payment Required. For buyers with full entitlement, you can purchase a home in Panama City with $0 down. In a market where median home prices hover around $300,000–$350,000, that eliminates a $60,000–$70,000 barrier that stops many buyers cold.
    2. No Private Mortgage Insurance (PMI). Conventional loans require PMI when you put down less than 20%, adding $150–$300 per month to your payment. VA loans have no PMI — ever. The VA’s federal guaranty replaces it.
    3. Competitive Interest Rates. Because the VA backs a portion of each loan, lenders take on less risk and typically offer rates 0.25%–0.50% below conventional rates. On a $300,000 loan, that can save tens of thousands of dollars over the life of the loan.

    Definition: VA Entitlement
    Your VA entitlement is the dollar amount the Department of Veterans Affairs guarantees to your lender if you default on your loan. Full entitlement means you have never used your VA benefit (or have fully restored it after paying off a prior VA loan), and there is no cap on how much you can borrow with zero down. Partial entitlement applies when you have an active VA loan or an unresolved default, and your zero-down borrowing power is calculated against the county conforming loan limit ($832,750 in Bay County for 2026).


    Are You Eligible? The Two-Part Qualification Process

    Step 1: Meet the VA’s Service Requirements

    Eligibility is based on your military service history. You generally qualify if you meet one of the following:

    • Veteran with 90+ consecutive days of active service during wartime, or 181+ days during peacetime
    • Active-duty service member with 90+ continuous days of service
    • National Guard or Reserve member with 6 years of honorable service, or who was activated under federal orders
    • Surviving spouse of a service member who died in the line of duty or from a service-connected disability

    Your first step is obtaining a Certificate of Eligibility (COE) — the official document that proves your entitlement to a VA-approved lender. The fastest route is through a VA-savvy lender who can pull it instantly via the VA’s WebLGY system. You can also apply at VA.gov or by mailing VA Form 26-1880. Check for updates: COE processing times and online portal availability may change — confirm current timelines at VA.gov.

    Step 2: Meet the Lender’s Financial Standards

    The VA does not set a minimum credit score, but lenders do. Most require a FICO score of 620 or higher, though some will work with scores as low as 580 with strong compensating factors. The VA uses a 41% debt-to-income (DTI) ratio as a guideline, but this is not a hard ceiling — lenders also evaluate your residual income (money left over after all major expenses), which is a uniquely VA concept designed to ensure you can afford daily living costs after your mortgage payment.


    The VA Funding Fee: What You’ll Pay (and Who Pays Nothing)

    Most borrowers pay a one-time VA funding fee, which can be rolled into the loan amount. The rate depends on your down payment and whether this is your first VA loan use:

    Down Payment First-Time Use Subsequent Use
    Less than 5% (0% down) 2.15% 3.30%
    5% – 9.99% 1.50% 1.50%
    10% or more 1.25% 1.25%

    As of this writing, these rates are current for 2026. Check for updates at VA.gov annually.

    Importantly, veterans receiving VA disability compensation, eligible surviving spouses, and active-duty Purple Heart recipients are completely exempt from the funding fee. This exemption is noted on your COE and can save thousands of dollars at closing.


    The Tyndall AFB Factor: Why Panama City Is a Prime VA Loan Market

    Tyndall Air Force Base is undergoing one of the most ambitious military construction projects in U.S. history. Following the devastation of Hurricane Michael in 2018, the “Base of the Future” rebuild — featuring 120 new, hurricane-resilient facilities — is nearing completion in 2026. The base accounts for roughly 34% of Bay County’s economy and supports over 28,000 jobs, making it the dominant force in the local housing market.

    For service members stationed at Tyndall, Basic Allowance for Housing (BAH) is a critical piece of the financing puzzle. BAH is tax-free income, and lenders can “gross it up” by approximately 25% when calculating your qualifying income — significantly boosting your buying power.

    2026 BAH Rates for Panama City (MHA: FL063)

    • E-6 with dependents: $2,442/month
    • O-3 with dependents: $2,709/month

    Check for updates: BAH rates are set annually by the DoD. Confirm current rates at the Defense Travel Management Office website before budgeting.

    An E-6’s BAH alone, when grossed up, can support a VA loan of approximately $275,000–$300,000 depending on current interest rates and other debts. Combined with base pay, most mid-career service members can comfortably qualify for homes in Panama City’s most popular neighborhoods, including Lynn Haven, Callaway, and Parker.


    The Panama City Coastal Risk Filter: A VA Buyer’s Checklist

    Buying near the Gulf Coast introduces property-specific risks that can affect your VA loan approval. Use this checklist before making an offer on any Panama City home:

    • ✅ Check the FEMA Flood Zone. Look up the property at FEMA’s Flood Map Service Center or Bay County’s GIS portal. Homes in Zone AE or Zone VE are in high-risk areas and will require mandatory flood insurance for the life of your VA loan.
    • ✅ Verify the property is not in a CBRS zone. Properties within the Coastal Barrier Resources System are generally ineligible for VA financing due to extreme storm surge and erosion risk.
    • ✅ Assess the roof age and condition. The VA appraiser will flag any roof with less than three years of estimated remaining life. In a coastal market, this is a common repair requirement.
    • ✅ Check for lead-based paint. Homes built before 1978 — common in older Panama City neighborhoods — must be free of chipping or peeling lead paint to meet VA Minimum Property Requirements (MPRs).
    • ✅ Confirm functional utilities. Electrical, plumbing, and HVAC systems must be operational and safe. Post-hurricane repairs that were done without permits can create issues at appraisal.
    • ✅ Budget for flood insurance separately. Flood insurance is not included in standard homeowner’s insurance. In high-risk zones, NFIP policies can add $1,500–$4,000+ per year to your housing costs.

    Definition: Flood Zone AE
    A FEMA-designated Special Flood Hazard Area (SFHA) with a 1% annual chance of flooding (also called the “100-year floodplain”). Homes in Zone AE that carry a federally backed mortgage — including VA loans — are legally required to maintain flood insurance. Many properties in Panama City Beach, the East End, and areas near North Bay fall within Zone AE boundaries.


    The VA Appraisal: What to Expect in a Coastal Market

    Every VA purchase requires a VA appraisal — a two-in-one process that establishes the home’s fair market value and confirms it meets the VA’s Minimum Property Requirements (MPRs). In Panama City, appraisers pay particular attention to:

    • Structural integrity — foundation stability and roof condition are scrutinized closely in a hurricane-prone area
    • Drainage — water must drain away from the foundation, not pool around it
    • Pest inspections — Florida’s climate makes termite activity a common MPR concern
    • Safe access — the property must have year-round, all-weather access

    If the appraiser requires repairs, they must be completed and re-inspected before the loan can close. This is not a dealbreaker, but it can add 1–3 weeks to your timeline. Work with a buyer’s agent who knows how to negotiate repair credits or seller concessions to cover these costs.


    Your Step-by-Step VA Loan Roadmap for Panama City

    1. Obtain your COE — through a lender, VA.gov, or by mail
    2. Get pre-approved — choose a lender with demonstrated VA loan experience in Florida
    3. Partner with a local agent — find a Panama City REALTOR® who understands VA appraisal requirements and coastal property nuances
    4. Search with MPRs in mind — prioritize well-maintained homes to reduce appraisal repair risk
    5. Make an offer — your pre-approval letter signals credibility to sellers
    6. VA appraisal and underwriting — typically 10–14 business days; address any MPR repairs promptly
    7. Final walkthrough and closing — review all closing disclosures carefully; confirm your funding fee exemption status if applicable

    From pre-approval to closing, a smooth VA purchase in Panama City typically takes 30–45 days. Complex appraisals or required repairs can extend this to 60 days.


    Common VA Loan Mistakes to Avoid in Panama City

    • Choosing a lender unfamiliar with VA loans. Not all lenders are VA-savvy. An inexperienced loan officer can misread entitlement calculations or cause unnecessary delays. Ask specifically how many VA loans they closed in the past 12 months.
    • Assuming “no down payment” means “no costs.” You will still pay for the appraisal, title insurance, recording fees, and potentially the funding fee. Budget 1%–3% of the purchase price for closing costs.
    • Skipping the flood zone check. Discovering a mandatory flood insurance requirement after you’re under contract can significantly change your monthly payment math.
    • Overlooking the residual income requirement. Even if your DTI looks fine, lenders must verify you have enough left over each month for living expenses. Know your numbers before applying.

    The VA loan is one of the most valuable benefits earned through military service, and in Panama City’s dynamic real estate market, it can be a decisive competitive advantage. Whether you’re PCS’ing to Tyndall AFB, retiring in Bay County, or returning home after service, this benefit is designed to help you build equity and stability — with terms no conventional loan can match.

    Last updated: April 2026. VA loan guidelines, funding fee rates, and BAH figures are subject to annual revision. Always verify current figures with a VA-approved lender and at VA.gov before making financial decisions.


    Related Reading

  • Buying a Florida Condo in 2026? Don’t Skip the New Milestone Inspection Paperwork

    Buying a Florida Condo in 2026? Don’t Skip the New Milestone Inspection Paperwork

    Last updated: April 2026. Check for updates as Florida’s condo safety regulations continue to evolve.

    If you’re shopping for a condo in Panama City or Panama City Beach, the rules of the game have fundamentally changed. Florida’s sweeping condo safety reforms — triggered by the 2021 Champlain Towers South collapse in Surfside — are now fully in effect. For buyers in 2026, understanding the new Milestone Inspection and Structural Integrity Reserve Study (SIRS) requirements isn’t optional. It’s the difference between a sound investment and a financial nightmare.


    Key Takeaways

    • Florida requires Milestone Inspections for all condo buildings 3+ stories — triggered at 25 years for coastal buildings (most Panama City Beach condos) and 30 years for inland buildings.
    • Associations must complete a Structural Integrity Reserve Study (SIRS) every 10 years and can no longer waive or underfund structural reserves.
    • Buyers have a 7-business-day review window to examine association documents — use every day of it.
    • A “two-tier” condo market is emerging in Panama City: compliant buildings command premiums; non-compliant buildings struggle to attract buyers and lenders.
    • Always confirm a building is “warrantable” with your lender early — non-warrantable status can kill financing or force costly loan products.
    • Special assessments are surging as associations catch up on deferred maintenance — your due diligence must uncover any pending assessments before you close.

    The Law Behind the Change

    Florida’s Building Safety Act (SB 4-D, enhanced by HB 1021) introduced two mandatory pillars for condo buildings three stories or taller: Milestone Inspections and Structural Integrity Reserve Studies.

    Definition: Milestone Inspection (MI)
    A structural safety assessment of a condo building’s primary load-bearing components, conducted by a licensed Florida engineer or architect. Phase 1 is a visual examination; Phase 2 is triggered only if Phase 1 reveals substantial structural deterioration and involves more intensive testing. Required at 25 years for coastal buildings and 30 years for all others, then every 10 years thereafter.

    Definition: Structural Integrity Reserve Study (SIRS)
    A financial planning document assessing the condition, remaining useful life, and estimated replacement cost of a building’s critical structural components — roof, load-bearing walls, plumbing, electrical, waterproofing, and windows. As of January 1, 2025, associations can no longer vote to waive or reduce these reserve contributions.

    What the Timeline Means for Panama City Buyers

    Nearly every beachfront or near-beach condo in Panama City Beach falls within the three-mile coastal zone, triggering the accelerated 25-year inspection threshold. Given that significant condo construction occurred along the Emerald Coast in the late 1990s and early 2000s, a large number of Panama City Beach buildings are now in or approaching their inspection window. Check for updates on any deadline extensions from the Florida DBPR.


    Panama City’s New Two-Tier Condo Market

    The new laws are reshaping the Panama City condo market visibly. Buildings with completed inspections, clean reports, and fully funded reserves are becoming premium assets — easier to finance, easier to insure, and more resilient in value. Buildings with deferred inspections, underfunded reserves, or troubling Phase 2 findings are facing serious headwinds: lender reluctance, longer market times, and downward price pressure.

    In Panama City’s coastal environment, where salt air, humidity, and hurricane exposure accelerate structural wear, the gap between well-maintained and neglected buildings is especially stark. The building’s compliance status is now as important as the unit’s interior finishes.


    The Panama City Condo Buyer’s “Inspect, Analyze, Protect” Framework

    Use this three-part framework to structure your due diligence on any Panama City or Panama City Beach condo purchase:

    1. Inspect: Evaluate the Building’s Physical Health

    • Obtain and read the complete Milestone Inspection report — including any Phase 2 findings and the repair plan.
    • Hire your own independent inspector experienced with Florida coastal condominiums.
    • Look for visible signs of water intrusion, concrete spalling, rust staining, or deteriorating balcony railings.
    • Ask specifically about roof age — in Panama City Beach, roofs take a beating from salt air and storm exposure.

    2. Analyze: Evaluate the Association’s Financial Health

    • Review the SIRS: What percentage funded is each structural component? Under 70% with less than 5 years of useful life remaining is a serious red flag.
    • Read board meeting minutes (last 24 months) for any mention of pending or discussed special assessments.
    • Compare monthly dues to similar buildings — unusually low dues often signal an imminent dues increase or special assessment.
    • Ask the seller to disclose in writing any known special assessments, whether levied or merely discussed.

    3. Protect: Secure Your Legal and Financial Position

    • Confirm with your lender early that the building is “warrantable” under Fannie Mae/Freddie Mac guidelines. Check for updates, as lender guidelines on condo warrantability continue to evolve.
    • Use your full 7-business-day document review period — never waive this right.
    • Engage a qualified Florida real estate attorney to review all association documents and your purchase contract.
    • Ask whether the association has applied for the My Safe Florida Condo Program, which offers grants for hurricane mitigation improvements that can lower insurance premiums.

    Red Flags That Should Give You Pause

    Even in a competitive Panama City market, negotiate hard — or walk away — if you encounter:

    • No completed Milestone Inspection for a building past its required age threshold
    • A Phase 2 inspection with unresolved findings and no clear repair timeline
    • Reserve funding below 70% for any structural component with a short remaining useful life
    • A pattern of special assessments in the board minutes over the past 3–5 years
    • Monthly dues that seem unusually low compared to similar beachfront buildings
    • Non-warrantable building status, which limits your financing options and future resale pool

    What This Means for Condo Prices in Panama City

    The new laws are directly impacting valuations across the Panama City condo market. Many associations are levying special assessments to fund repairs identified by inspections and to catch up on years of underfunded reserves, putting downward pressure on prices in some older buildings. However, for buyers willing to do the homework, this creates real opportunity.

    A unit in a building with a clean inspection report, a fully funded SIRS, and a financially transparent association is a genuinely superior asset. Higher monthly dues, while initially off-putting, are increasingly a positive signal — they reflect the true cost of maintaining a coastal building and protect your investment from sudden, large assessments down the road. In Panama City’s condo market, the paperwork is now part of the product.

    As of this writing (April 2026), Florida’s condo safety regulations are still being interpreted and enforced. Check for updates from the Florida DBPR and consult a licensed Florida real estate professional for the most current guidance.

    Related Reading

  • The Tables Have Turned: 5 Signs It’s a Buyer’s Market in Panama City (and How to Take Advantage)

    The Tables Have Turned: 5 Signs It’s a Buyer’s Market in Panama City (and How to Take Advantage)

    If you’ve been watching the Panama City real estate market from the sidelines, waiting for the right moment to make your move, that moment may have arrived. After years of fierce competition and bidding wars, the market has shifted decisively in favor of buyers. Homes are sitting longer, sellers are negotiating, and inventory is providing options that simply didn’t exist 18 months ago.

    But how can you tell if it’s truly a buyer’s market—and more importantly, how do you leverage these conditions to secure the best possible deal on your Panama City home? Let’s break down the five unmistakable signs that buyers are in the driver’s seat, and the strategic moves you should make right now.

    Key Takeaways

    • Days on Market are Climbing: Homes in Panama City Beach now average 74-117 days on market, giving buyers time for thorough due diligence
    • Negotiation Power is Real: Sale-to-list price ratios in the low-to-mid 90% range mean sellers are accepting below asking price
    • Inventory is Favorable: Despite a slight decrease in active listings, the overall supply provides meaningful choice for buyers
    • Act Strategically, Not Desperately: While conditions favor buyers, pending sales are up 28% year-over-year—this window won’t last forever
    • Flood Zone Due Diligence is Non-Negotiable: In coastal Panama City, verifying flood risk and securing proper insurance is essential to any purchase

    Sign #1: Homes Are Sitting on the Market Longer

    One of the clearest indicators of a buyer’s market is the amount of time properties spend listed before going under contract. In Panama City Beach, the median days on market (DOM) has settled at 74 days, with averages ranging from 88 to 117 days depending on property type and location. Compare this to the frenzied seller’s market of 2021-2022, when homes routinely went under contract within days—sometimes with multiple offers sight unseen.

    What this means for you: You have time. Time to schedule a thorough home inspection. Time to research the neighborhood, verify school zones, and check flood maps. Time to review seller disclosures and HOA documents without pressure. In Panama City’s coastal environment, where flood risk and insurance costs can make or break a deal, this breathing room is invaluable.

    Definition: Days on Market (DOM)
    Days on Market refers to the number of calendar days between when a property is first listed for sale and when it goes under contract with a buyer. A higher DOM typically signals a buyer’s market, while a lower DOM indicates strong seller leverage.

    Sign #2: Sale-to-List Price Ratios Favor Negotiation

    In Panama City, the sale-to-list price ratio—the percentage of the asking price that a home actually sells for—is hovering in the low-to-mid 90% range for many properties, with an average around 96%. This is a significant departure from the 100%+ ratios seen during peak seller’s markets, when buyers routinely offered over asking price just to compete.

    Translation: Sellers are accepting offers below their asking price. This creates a negotiation opportunity, especially for properties that are overpriced, need updates, or have been on the market for an extended period. A well-informed buyer who understands comparable sales in neighborhoods like Southport, Lower Grand Lagoon, or Bay View can craft an offer that reflects true market value—not wishful thinking.

    The Panama City Negotiation Framework

    To maximize your leverage in this market, follow this three-step approach:

    1. Research Comparable Sales: Work with your agent to pull recent sales (last 90 days) of similar homes in the same neighborhood. Pay attention to price per square foot, condition, and proximity to the coast.
    2. Identify Property-Specific Weaknesses: Does the home need a new roof? Is it in a high-risk flood zone requiring expensive insurance? Are there deferred maintenance issues? These are negotiation points.
    3. Make a Data-Driven Offer: Base your offer on comps and condition, not emotion. In a buyer’s market, a reasonable offer backed by data is far more effective than a lowball that alienates the seller.

    Sign #3: Inventory Levels Provide Meaningful Choice

    While active listings in Panama City Beach saw a modest 6.5% year-over-year decrease to 1,756 properties, the overall inventory remains favorable for buyers. More importantly, experts forecast inventory levels to increase by 5-10% through the remainder of 2026, further expanding your options.

    This is particularly significant for buyers with specific needs—whether you’re searching for a family home in a top-rated school zone like Southport, a coastal property in Gulf Lagoon Beach, or an affordable starter home in Bay View. Choice means you’re not forced to compromise on your must-haves or settle for a property that’s “close enough.”

    Neighborhood Spotlight: Where to Focus Your Search

    Panama City offers diverse neighborhoods at varying price points. Here’s where savvy buyers are finding value in 2026:

    • Southport: Median price of $323,973. Family-friendly with good public schools (Bay School District, rated “A” by the state), high homeownership rates, and above-average safety. A higher vacancy rate (13.7%) means more inventory to choose from.
    • Bay View: More affordable at $190,918 median price. Ideal for first-time buyers or investors. Primarily small-to-medium single-family homes and apartments.
    • Lower Grand Lagoon: Coastal living with access to top-rated schools. Premium pricing but strong long-term value in a desirable location.

    Sign #4: Sellers Are Motivated and Flexible

    When homes sit on the market for months rather than days, seller psychology shifts. What was once a “take it or leave it” attitude becomes a willingness to negotiate—not just on price, but on terms that matter to buyers.

    In the current Panama City market, you may find sellers willing to:

    • Cover a portion of your closing costs (typically 2-3% of the purchase price)
    • Provide a credit for repairs identified during the home inspection
    • Offer flexibility on the closing date to accommodate your timeline
    • Include appliances, furniture, or other personal property in the sale
    • Pay for a home warranty to provide peace of mind on major systems

    These concessions can save you thousands of dollars and reduce the stress of moving into a new home. The key is to work with an experienced local agent who understands which sellers are truly motivated and how to structure an offer that appeals to their specific situation.

    Sign #5: Pending Sales Are Rising—But You Still Have Time

    Here’s the nuance: While all signs point to a buyer’s market, pending sales in Panama City Beach jumped 28% year-over-year. This tells us that buyer demand is surging, likely driven by easing mortgage rates (projected to remain in the 6.0-6.8% range through 2026) and pent-up demand from buyers who sat out the market during the high-rate environment of 2023-2024.

    What this means: The buyer’s market window is real, but it’s not infinite. As more buyers recognize the opportunity and re-enter the market, competition will increase, days on market will decrease, and negotiation leverage will erode. The time to act is now—but with strategy, not panic.

    Definition: Pending Sale
    A pending sale occurs when a buyer and seller have signed a purchase agreement and the home is under contract, but the transaction has not yet closed. A sharp increase in pending sales signals rising buyer demand and can foreshadow a shift toward a more competitive market.

    How to Take Advantage: Your Panama City Buyer’s Market Action Plan

    Recognizing a buyer’s market is one thing. Capitalizing on it requires preparation and execution. Here’s your step-by-step playbook:

    Step 1: Get Pre-Approved for a Mortgage (Not Just Pre-Qualified)

    This is the single most powerful move you can make. A pre-approval letter from a reputable lender demonstrates to sellers that you are a serious, financially qualified buyer. In a market where sellers have options, a pre-approved buyer will always win over someone who is merely “interested.”

    Pre-approval also clarifies your budget, preventing you from falling in love with a home you can’t afford. Work with a lender familiar with Panama City’s unique considerations, including flood insurance requirements and coastal property financing.

    Step 2: Partner with a Local Real Estate Agent

    A buyer’s agent who knows Panama City inside and out is invaluable. They can identify properties before they hit the major listing sites, provide insight into neighborhood trends, and negotiate on your behalf. Most importantly, they understand the local nuances—from flood zone designations to school district boundaries to HOA restrictions—that can make or break a purchase decision.

    Step 3: Conduct Rigorous Due Diligence

    In Panama City’s coastal environment, due diligence goes beyond a standard home inspection. You must also:

    • Verify the Flood Zone: Use the City of Panama City’s online tool to check the property’s flood zone designation and Base Flood Elevation (BFE). Properties in Special Flood Hazard Areas (SFHA) will require flood insurance, which can add hundreds of dollars to your monthly housing costs.
    • Review Seller Disclosures Carefully: Florida law requires sellers to disclose all known material defects, even in “as-is” sales. Pay close attention to disclosures about code enforcement actions, HOA issues, and structural concerns.
    • Understand Insurance Costs: Standard homeowner’s insurance does NOT cover flood damage. Get quotes for both homeowner’s and flood insurance before making an offer. Panama City Beach participates in the NFIP’s Community Rating System, which can provide discounted flood insurance premiums.
    • Check School Zones: If you have children, verify the specific school zone for the property. The Bay School District is rated “A” by the state, but individual school assignments vary by address.

    Step 4: Make a Strategic Offer

    Your offer should be informed by market data, property condition, and seller motivation. In a buyer’s market, you have leverage—but a lowball offer can backfire. Instead:

    • Base your offer on recent comparable sales, adjusted for condition and location
    • Include a reasonable earnest money deposit (typically 1-3% of the purchase price) to show good faith
    • Request a home inspection contingency—never waive this, especially in coastal areas where hurricane damage and moisture issues are common
    • Consider asking the seller to cover a portion of closing costs or provide a repair credit based on inspection findings
    • Be flexible on closing date if it doesn’t impact your timeline—this can make your offer more attractive

    Step 5: Use the Inspection as a Negotiation Tool

    The home inspection is your opportunity to uncover issues that weren’t apparent during showings. In Panama City, pay special attention to:

    • Roof condition (critical in hurricane-prone areas)
    • HVAC systems (Florida’s heat and humidity are hard on equipment)
    • Signs of water intrusion or mold
    • Foundation and structural integrity
    • Compliance with coastal construction codes

    If significant issues are found, you can request that the seller make repairs, provide a credit at closing, or reduce the purchase price. In a buyer’s market, sellers are often willing to negotiate rather than risk losing the deal and putting the home back on the market.

    The Bottom Line: Act Now, But Act Smart

    The Panama City real estate market in 2026 is offering a window of opportunity that hasn’t existed in years. Homes are staying on the market longer, sellers are negotiating, and inventory is providing meaningful choice. But with pending sales up 28% and buyer demand rising, this favorable climate won’t last indefinitely.

    The key is to move with purpose, not panic. Get pre-approved, partner with a knowledgeable local agent, conduct thorough due diligence on flood risk and property condition, and make data-driven offers that reflect true market value. By following this strategic approach, you can take full advantage of the buyer’s market and secure a home in Panama City on terms that work for you.

    Last updated: March 27, 2026. Market conditions and statistics are subject to change. Always verify current data with a licensed real estate professional and conduct independent due diligence before making a purchase decision.

    Related Reading